
Originally published April 22, 2024. Last updated Sept. 17, 2026.
From pre-seed to Series D, this complete guide walks Canadian founders through every startup funding stage, including what investors expect, how much to raise, and how to choose the right capital at the right time.
Key takeaways
- Startup funding progresses through distinct stages, each with its own milestones, instruments, and investor expectations, from pre-seed and seed (typically SAFEs and convertible notes) through Series A and later (priced equity rounds with consequential term sheet terms).
- Startup funding in Canada can be broken down into two basic categories: dilutive and non-dilutive. Dilutive financing means capital is raised in exchange for a portion (equity) of ownership in the company, while non-dilutive funds are acquired without loss of ownership.
- The benchmarks for each round have risen. Seed investors now expect ~$25,000–$50,000 in monthly recurring revenue (MRR) and a repeatable sales motion, while Series A investors look for $150,000–$300,000+ MRR and a path to break-even within 18–24 months.
- Canada’s funding environment has structural gaps, with seed rounds averaging ~$3 million (smaller than U.S. counterparts). While these gaps are partly offset by non-dilutive programs like SR&ED, domestic firms generally can’t lead rounds above ~$30 million. This makes international investors essential at Series B and beyond.
- Fund dynamics shape fundraising timing. A VC fund’s vintage indicates how much it has remaining for new investments, and newly announced funds might signal openings for early-stage cheques that older funds can’t make.
Embarking on a new venture can be thrilling, but without any sense of where you’re headed, you’ll likely find yourself spinning in circles or hopelessly lost.
The journey of a startup founder is a sequence of stages, each one a critical part of a longer journey. From pre-seed through seed, from Series A to D, each phase comes with its own milestones, expectations, and potential setbacks. Staying on the right trajectory requires understanding how each stage flows into the next and what’s required to make each work to your company’s advantage.
Fundraising is never easy, and the challenges are as great as ever. In Canada, the domestic funding environment has tightened considerably, with Canadian VC funds raising just over $2 billion in 2025 — a considerable amount, but nowhere near the $7+ billion at its 2021–2022 peak. This makes tailoring your strategy to each stage even more critical.
This guide explains how to raise capital and how to get startup funding in Canada. You’ll learn how the stage ladder works, the difference between dilutive and non-dilutive capital, and how to maximize your own startup funding strategy.
Consider this your fundraising roadmap, keeping you oriented as you head out on your entrepreneurial adventure.
Why do startups need to raise funding?
Startups raise funding because most are cash-burning and unprofitable by design — they invest heavily upfront to capture a market before revenue catches up. Unlike conventional companies, tech startups launch intending to disrupt a market with an innovative product, and they expect to grow and scale at an accelerated pace, which requires substantial capital.
While personally financing a startup (also called bootstrapping) might be sufficient at pre-seed, and sometimes even seed, most founders soon realize they need to raise capital to grow and maintain momentum.
Startups therefore look for outside funding to help them build their product and team, reach market milestones, and access the capital, networks, and expertise of investors who can help them scale effectively.
A company’s fundraising approach changes with its shifting needs. In the early stages, it’s often raising funds simply to stay afloat — extending its cash runway, or the length of time a company can operate before its cash reserves are exhausted at its current spending, or burn rate. Moving into the later stages, the emphasis is often on accelerating and scaling, requiring growth capital.
While it’s important for companies to proactively pursue revenue sources, it’s just as crucial that they maintain strategic clarity on how their fundraising efforts correspond to their current step in the ladder.
“There’s no right or wrong when it comes to financing your startup, but you need to be strategic about it because the impact is long-lasting. Choices you make today are going to impact tomorrow.”
How does startup funding work?
There are no hard-and-fast rules on when a founder should start seeking outside funding. While some startups can thrive without outside capital for a long time, others may need to acquire funding within the first year of operations.
Funding is typically structured as a sequence of rounds, each tied to a stage of company maturity, where each round raises more capital at a higher valuation in exchange for equity. The cadence between rounds is typically 12–18 months, but not every startup will follow the same progression or pace through these stages; some companies might skip certain rounds, while others might stall at certain junctures.
“As your company ramps up and becomes more complex as it scales, different funders will come into your life cycle,” says Laith Shukri, Director of Early Stage Banking at RBCx. “There’s no right or wrong when it comes to financing your startup, but you need to be strategic about it because the impact is long-lasting. Choices you make today are going to impact tomorrow.”
Founders should be on the lookout for any new opportunities that might arise. The government might suddenly launch a new funding program with a narrow application window, or a venture capital (VC) investor might announce a new fund that allocates pre-seed or seed investments into startups. Keeping an eye on the startup ecosystem and talking to peers can help determine when it’s the ideal time to seek funding.
Whatever the funding avenue they’re pursuing — a family friend, government grant, an accelerator, a venture capitalist, or a venture debt lender — a startup will need to make a persuasive case for why their company is a credible investment. If they can’t, it might not be the right moment to pursue funding from that particular source. It also might signal that the company and its founder(s) need more time to reflect on the value they’re offering prospective investors. For a fuller overview of each funding source, see our guide to the sources of startup funding.
What are the stages of startup funding?
Use this stage navigator as your quick reference. Each stage links to a dedicated deep-dive article — explore the one that matches where your company is today.
- Pre-seed funding: Earliest capital (typically $250K–$1M) from founders, friends and family, accelerators, and angels, usually raised on SAFEs to validate an idea and build toward product-market fit.
- Seed funding: The first formal round (~$3M in Canada) to establish product-market fit, raised via SAFEs, convertible notes, or priced equity with seed-stage VCs, angels, and micro-funds.
- Series A funding: The first institutional priced equity round (~$22M median in Canada) to finance repeatable growth after product-market fit is proven.
- Series B funding: Scaling capital ($20M–$50M) for companies with consistent revenue, focused on unit economics, market expansion, and a path to profitability.
- Series C funding: Growth-stage capital (~$50M median in Canada) to establish market leadership through acquisitions, geographic expansion, and major product launches.
- Series D and beyond: Pre-IPO scale capital for a final push toward public markets or to remain private longer, with emphasis on profitability, governance, and public-market readiness.
Pre-seed funding
Pre-seed funding is a startup’s earliest capital, typically sourced from founders, friends and family, accelerators, and/or angel investors. It can be used for early endeavours as building a product, validating a core idea, or working toward product-market fit signals.
Pre-seed fundraising is typically in the range of $250,000 to $1 million. In 2025, 92% of U.S. pre-seed rounds saw simple agreements for future equity (SAFEs) used as the primary funding instrument.
Pre-seed investors are betting primarily on the founding team and a working prototype, with expectations centred on team pedigree, problem clarity, and early traction rather than revenue.
Seed funding
Seed funding is the first formal capital a startup raises. It’s used to establish product-market fit, with a higher proportion of dedicated seed-stage VCs participating alongside angels and micro-funds.
Seed funding is usually structured through convertible debt, SAFEs, or priced equity rounds. Each startup investment vehicle has its own level of investor risk appetite and expected return, and it’s advised to understand the potential suitability of each.
The average seed round size among Canadian early-stage founders has averaged approximately $3 million in recent quarters, lower than U.S. counterparts, though this gap is partly offset by Canada’s non-dilutive funding stack (including grants and other supporting programs), which let founders extend runway without giving up equity.
Founders raising seed should be prepared to show that not only is their business model viable, but that their early customers are repeatable and referable, since investors expect sustained sales motion and consistent monthly recurring revenue.
Series A funding
Series A is the first formal institutional equity round, raised after strong signs of product-market fit to finance growth in areas such as hiring, product enhancement, and maturing the business.
With Series A marking the final round of early-stage financing, founders should expect detailed diligence on cohort retention, sales efficiency, and gross margin. Investors expect clarity from founders in the form of repeatable go-to-market motion, early proof of sales efficiency, and evidence that they understand where growth stalls under pressure and how invested capital will be allocated to avoid bottlenecks.
A pitch deck at this stage therefore needs to hold up to detailed scrutiny, with firm metrics rather than vision storytelling. Because the round is priced, terms around liquidation preferences, board composition, and pro-rata rights now carry real consequences, making term sheet negotiation as important as the valuation itself. Once priced, every new share issued affects the ownership of existing shareholders, which is why keeping an accurate cap table is essential from this stage onward.
According to Shoutex, the median Series A round for Canadian startups in 2025-2026 saw an increase to approximately $22 million, up from ~$15 million just a few years earlier. This doesn’t mean investors are necessarily taking on greater risk, but they are increasingly focusing their capital into fewer companies that have already cleared multiple filters at earlier stages.
Series B funding
Series B is the round at which companies generating consistent revenue find the capital needed to expand and scale, enter new markets, and build out the team.
At Series B, investor expectations move from rapid growth to scalable unit economics and a clear path to profitability. Follow-on financing from the previous round’s investors can be one important and beneficial signal of confidence. The stakes and scrutiny are higher, with investors probing channel economics, payback periods, and the repeatability of the go-to-market motion.
According to Carta, a typical Series B raise in 2026 falls between $20 million and $50 million on a post-money valuation of $100 million to $175 million, with a median round size of ~$30 million and median pre-money valuation of ~$119 million.
Canadian venture firms are generally not positioned to inject more than ~$30 million, so later rounds frequently require international investment. Founders should therefore begin cultivating those relationships early during Series A, rather than delaying until they need the capital.
Series C funding
Series C is the round where companies establish market leadership, with capital raised at this stage used for acquisitions, geographic expansion, and major product launches.
New growth-stage investors, including venture debt entities like private equity firms and sovereign funds as well as traditional institutions like banks, might sign on at Series C, investing larger amounts in more mature companies that are closer to an exit. Investor expectations shift to market leadership, defensible moats, and clear paths to IPO or acquisition, and their diligence tends to focus on competitive positioning, regulatory exposure, and the durability of revenue under stress.
Data from Osler shows the median Series C raise in Canada is approximately $50 million, though the market has been disproportionately skewed by AI-driven rounds, which have pushed the average above $140 million.
Series D and beyond
Series D (and later) rounds are pre-initial public offering (IPO) scale capital, commonly used for a final push toward public markets, extending runway, or to remain private for longer while still expanding.
Not every company reaches this stage, since many are acquired or go public earlier. The emphasis in Series D shifts to profitability, governance, and elements required for reaching public-market investors, including audited financials, board independence, and reporting cadence that can withstand scrutiny from regulators and institutional shareholders.
Series D and beyond represented only 10% of all Canadian financings in 2025, but accounted for 43.6% of all dollars invested, at US$1.96 billion.
Dilutive vs. Non-Dilutive Funding: What Every Founder Needs to Know
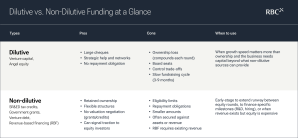
Dilutive funding is capital raised in exchange for ownership (equity) in the company. Non-dilutive funding is capital acquired without giving up ownership — such as grants, tax credits, and loans — though it may carry fees, interest or repayment obligations.
Dilutive financing is typically done by issuing shares that decrease the ownership of existing shareholders (also referred to as dilution). It often occurs with other changes within the company, such as meeting investors’ expectations and providing them board representation. Founders who are resistant to reducing their ownership might instead lean toward non-dilutive financing. Types of dilutive financing include venture capital and angel investors, and tend to dominate from the seed stage onward.
Non-dilutive financing means capital is acquired without any loss of ownership of the company, but it might come with fees and interest. Additionally, non-dilutive funding, like loans, may need to be repaid over a set period. Types of non-dilutive financing include loans, grants (including Scientific Research and Experimental Development [SR&ED] grants), tax incentives, and some forms of venture debt, and are generally most accessible in early stages.
What are the main sources of funding for an early-stage startup?
Startups will typically rely on multiple funding vehicles throughout their lifecycle, each with its own level of risk and potential return.
Personal investing
Startup founders typically rely on their own personal funds to start growing their initial idea into a viable business. This can be financially challenging, as most startups are cash-burning. However, it also ensures the founder retains autonomy over major decisions in the business they’ve started. Bootstrapping also lets founders concentrate on business growth, as raising capital is often time-consuming and demanding.
In the early stages of growth, some founders may also turn to family or friends for funding. While such funding can be helpful (when available), this could require giving up equity in exchange for this capital or providing specific repayment terms based on when the company becomes profitable.
Angel investors
Angel investors invest their own money into an early-stage startup. These are usually wealthy individuals that provide seed money to promising companies in exchange for ownership, sometimes via SAFEs or convertible notes (see below). These instruments require less paperwork than formal rounds and offer more flexibility to both investors and startups.
SAFEs and convertible notes
SAFEs and convertible notes are ideal funding options for startup founders seeking capital after they’ve hit their bootstrapping limits but before they’re ready to pitch VCs in a formal equity raise. These two instruments enable an investor to provide capital that can later be converted to equity. For a full comparison, see our guide to SAFEs and convertible notes.
In short: a SAFE is an equity instrument because the investor receives an ownership stake after the company completes a priced round. A convertible note, on the other hand, is a debt instrument because it has an interest-bearing loan and a maturity date by which the note must convert to equity or be repaid.
“These are basically like little IOUs, where you kind of kick the pricing down the line up until the next institutional round,” says Shukri.
Accelerators and incubators
Accelerators and incubators are organizations and programs that provide guidance and mentorship to help set up early-stage startups for long-term success. They also offer a valuable network of investors and experts that can be a key asset as the company scales and seeks funding. Startup founders must apply for the programs, many of which have a set duration, and should expect to invest significant time to engage fully in the program. Some of these programs also provide access to seed funding. Learn whether an accelerator is right for you.
Venture capital
Venture capital (VC) is a form of dilutive financing investors provide to private companies that demonstrate strong potential for growth and generating strong returns. In exchange for their capital, VC investors receive an ownership stake in the business along with other provisions, such as board representation. For a deeper primer, see Venture Capital: What Startups Need to Know.
For many startups, the first formal VC financing round is Series A; however, some VC funds invest in seed-stage startups. To acquire venture capital, founders must first pitch to investors. If a VC signals interest in investing, it carries out due diligence on the company and determines the valuation (the amount of money the company is worth). The valuation and all financing details are outlined in the VC term sheet; once both sides agree, legal documentation finalizes the investment. When the deal closes, the VC holds equity, is a shareholder, and may have a seat on the board. Founders should prepare to vet their investors — see our list of 25 questions to ask VCs when fundraising — and expect to be vetted in return. VCs will have their own line of questioning during diligence; reviewing the 75 common questions venture capitalists ask before investing in a startup can help you walk in prepared.
Government grants and tax incentives
The federal government of Canada and provincial governments offer billions of dollars each year to Canadian businesses in various forms, ranging from grants to tax incentives to interest-free loans. A substantial portion of that funding is for tech-based companies. Startups that pursue these opportunities stand to gain much needed capital to finance their scaling ambitions.
Canadian government grants
Grants can come from federal, provincial or territorial, and even municipal governments. Startups must pre-qualify to be eligible to receive the investment, meaning they can’t start incurring any costs related to the funding request until the application is approved and awarded.
The application process for grants can be arduous and is often very competitive. Still, early-stage startups that monitor the various grant opportunities, and invest the time to apply, stand to gain helpful financial assistance.
One example of federal funding is the NRC-IRAP (National Research Council of Canada Industrial Research Assistance Program), which provides funding to support research and development projects by small- to medium-sized businesses at various stages of the innovation cycle. Successful applicants receive a financial contribution to share the costs of their research and development (R&D) project activities.
Canadian tax credits
Unlike grants, funds from tax credits are received after the dollars have been spent by the startup. The most well-known program in Canada is SR&ED, which offers tax incentives to encourage businesses to conduct research and development in Canada.
The SR&ED program delivered $4.5 billion in investment tax credits in fiscal 2024–2025 and $4.9 billion claimed ($4.6 billion allowed) in fiscal 2025–2026, across more than 24,000 claims.
“Sometimes you have programs that have specific intake, so you might get an announcement a couple of weeks before, ‘we’re opening up an intake for this specific area, this specific eligibility criteria,’ and you have six to eight weeks to apply for that.”
Eligibility and applying for government programs
Determining eligibility for the various government programs can be a huge task, and the incentives landscape is constantly evolving.
“I encourage [startups] to work with a service provider. I’ve seen companies decide they want to save money, so they do it themselves. It’s not as simple as you think, and the way you complete your short application does determine what the outcome is,” advises Jigna Shah, Partner in Deloitte’s Global Investment and Innovation Incentives (Gi3) practice.
“Sometimes you have programs that have specific intake, so you might get an announcement a couple of weeks before, saying ‘we’re opening up an intake for this specific area, this specific eligibility criteria,’ and you have six to eight weeks to apply for that,” says Shah. “There’s that narrow window of opportunity that if everything checks off, then you can apply and hopefully have a good chance of getting some funding. And then there are those [programs] that are on a rolling basis.”
Business loans
As a cash-burning business in the early stages of growth, it can be challenging to access conventional bank loans. However, there are programs that enable startups to acquire low-interest or no-interest loans. Programs may be limited to specific industries, geography, or other parameters. BDC, for example, offers non-dilutive financing to all varieties of businesses, with funds specifically tailored to tech startups.
Venture debt
Venture debt is a loan that gives startups a capital injection to extend their runway and reach more milestones before the next financing round. A startup should have recently completed an equity round and have an existing cash runway of more than 12 months to be considered for venture debt. For a deeper look, see our guide to navigating venture debt.
Like any startup loan, venture debt typically comes with covenants, conditions the lender imposes on the business. Understanding how debt covenants can affect startups before signing helps founders avoid restrictions that could limit their operating flexibility down the line.
Venture debt charges interest only on the money the company draws upon. While most loans are considered non-dilutive, venture debt can have a dilutive impact because it often comes with a nominal warrant (a warrant is a right, but not an obligation, granted to an investor or lender to purchase equity in the company at a fixed price for a specified period).
The value of venture debt can be crucial to a company’s progress.
“If you’re a fast-growing company, then you’re able to raise at an even better valuation later,” says Shukri. However, he cautions this might not be the right strategy for every company. “Are you growing enough that you know you need this?”
How to maximize your startup funding strategy
There are multiple paths to funding for startups, from pre-seed to pre-IPO. Here are three important tips to help founders take advantage of all the potential sources of funding available to startups in Canada.
1. Maximize non-dilutive funding first. Founders should maximize all their non-dilutive funding options, such as grants, tax incentives, and low-interest loans, before seeking investments or loans through a VC or bank. Not only does this potentially extend runway, it signals to lenders and investors that you’ve done your homework.
“Are you maximizing from this perspective before you go into dilutive? It shows up really well for a company looking to do a raise that you’ve done your due diligence and taken advantage of a number of these programs,” says Shah.
2. Use a grants service provider. SR&ED and grant applications are specialized and time-consuming, and the landscape is constantly evolving. A grants specialist with expertise in your particular industry can maximize claim value and free up more of your valuable time to instead focus on building.
3. Watch for a VC fund’s vintage. When the time comes to seek venture capital, look at the vintage (or age) of potential investors’ funds. “That should give you an idea of who has room to invest,” says Shukri. Funds that are four years in probably don’t have much, if any, dry powder remaining (“dry powder” refers to the unallocated capital reserves held by private equity funds, ready to be deployed into investments).
“Dry powder is then reserved for later stage investments to beef up the IRR (internal rate of return),” says Shukri. Aligning fundraising timing with actual fund dynamics can improve your odds. Also, watch for announcements on new funds, because that could translate to an opportunity for an early-stage startup.
The journey begins
Fundraising can take up a significant portion of a startup’s time, but the results can be tremendously beneficial. While fundraising is a necessary part of leading a successful venture, it’s just as important to stay focused on your business’s core principles, and your own priorities and values — and let those be the north star that guides the business. Ultimately, investors and lenders want to know the companies they invest in can stay the course, meet important milestones, and be relentless in their pursuit toward profitability.
RBCx offers support to startups in all stages of growth, backing some of Canada’s most daring tech companies and idea generators. We turn our experience, networks, and capital into your competitive advantage to help you scale and make a meaningful impact on the world. Speak with an RBCx Advisor to learn more about how we can help your business grow.
FAQs
RELATED TOPICS
Other articles you may be interested in


 © 2026 RBC All rights reserved.
